


PMMI 2026: US Packaging Machinery Hits $11.7B
The Headline Numbers
PMMI’s 2026 Packaging State of the Industry Report puts the U.S. packaging machinery market at an estimated $11.7 billion in shipment value for 2025. Food remains the dominant end market at roughly 44% of the total, with food machinery shipments alone estimated at $5.1 billion in 2025 and projected to climb to about $7.1 billion by 2031. The report also tracks a strengthening Canadian market, where domestic packaging machinery shipments reached about $1.2 billion in 2025—up 3.6% year over year—and are expected to approach $1.4 billion by 2027.
The North American figures are tightly coupled. Canada imported roughly $504 million in packaging machinery in 2025, with the United States supplying 30% of that total, while 91% of Canadian packaging machinery exports went to the United States. The U.S. also imported $3.8 billion in packaging machinery during 2025, a reminder that the equipment market is now a global sourcing game rather than a purely domestic one.
What’s Driving Equipment Decisions in 2026
The report identifies a short list of forces shaping capital investment. SKU proliferation sits at the top: social-media-driven demand and shorter product lifecycles are pushing manufacturers toward equipment that handles more formats, more single-serve and grab-and-go options, and more frequent changeovers. Behind it sit workforce constraints, emerging AI applications, tighter capital discipline, sustainability and regulatory requirements, and rising input costs.
The through-line is a quote from Jorge Izquierdo, PMMI’s vice president of market development: packaging and processing companies are “being asked to do more SKUs, more formats and more automation—all while maintaining productivity and making every capital investment count.” That tension explains why modular, reconfigurable machinery is replacing monolithic, single-purpose lines.
Flexibility Is the New Currency
Shorter runs and format variety are the clearest drivers in the data. The report highlights a decisive shift away from dedicated equipment toward systems engineered for faster changeover and operational flexibility. In practical terms, that means machines with stored job recipes, tool-free adjustment, and servo-driven positioning—the difference between a five-minute changeover and a thirty-minute one on a mixed-batch afternoon.
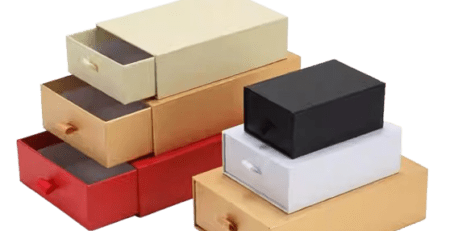
For rigid box, paper bag, and book cover converters, the same logic applies. A line that switches between box sizes and board grades without rebuilding tooling converts short-run orders from a bottleneck into billable production.
Labor and the Automation Push
Workforce shortages remain a primary driver of automation, especially for repetitive and physically demanding tasks. The report points to palletizing as a priority application, with robotic systems and cobots improving throughput and ergonomics, and to the convergence of end-of-line functions—case erecting, packing, and sealing increasingly folded into integrated systems. Autonomous mobile robots are also linking production lines to warehousing and dispatch.
AI is moving from promise to practice in targeted ways: retaining institutional knowledge from retiring operators, generating equipment specifications from past projects, and supporting real-time troubleshooting. These tools extend a constrained workforce rather than replace specialist knowledge.
Sustainability and EPR Pressure
Extended Producer Responsibility policies, single-use plastic restrictions, and material-reduction targets are reshaping equipment requirements. Converters are being asked to run a wider range of substrates and formats as packaging specifications evolve, which means machines must tolerate board grades, coatings, and recyclable paper materials that legacy lines could not process. The report frames this as both a compliance burden and a demand signal: equipment that can switch between paper and conventional substrates is increasingly a procurement requirement, not a nice-to-have.
What It Means for Converters
The report’s findings translate directly to the rigid box, paper bag, and book cover segment. Flexibility, labor savings, and substrate adaptability are now the three levers that separate competitive converters from struggling ones. A rigid box making machine that automates forming, wrapping, and pressing in one pass, or a fully automatic folding box flanking machine built for fast changeover, delivers exactly the flexibility-and-labor economics PMMI describes.
To align your line with the automation and substrate trends behind the $11.7 billion market, contact our team at +86-13809820550 (WhatsApp) with your maximum format, board grade, and target pieces per shift.

Leave a Reply